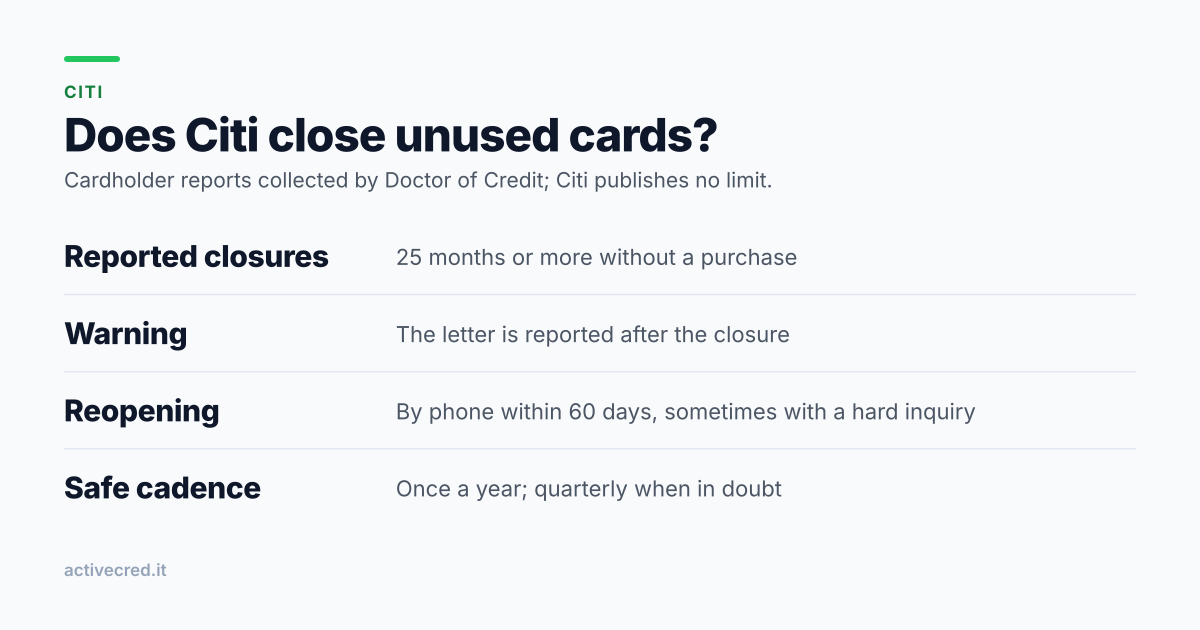
Citi closes credit cards that go unused, but not at six months, as this Journal and much of the web once said. Cardholder reports collected by Doctor of Credit put Citi closures at 25 months or more. The letter is reported to arrive after the closure, and reopening is reported within 60 days. A purchase once a year keeps a Citi card inside every report.
Citi is reported to close unused cards after 25 months or more, and to send the letter only afterwards. Reopening by phone is reported within 60 days, sometimes with a hard inquiry, and ThankYou points can be redeemed for 60 days. ActiveCred charges each Citi card once a year by default.
Keep a Citi card open or jump to pricingWhat the record shows
The best-documented Citi case is a Dividend card closed after more than 25 months without a purchase. A Citi chat representative gave the same figure, and other cardholders report it too. The reports are collected by Doctor of Credit and kept by ActiveCred in a public data file checked on November 14, 2026. They are reports, not Citi policy, and rest on few accounts.
Citi store cards are a separate line. Doctor of Credit's author reports a Citi-issued Best Buy card left open for years without use, while other Citi store cards are reported closed. The record does not give a window for them.
Doctor of Credit's list dates from 2019, with reader reports added since, and a bank can change its practice without announcing it. At Citi, where the window is long, the temptation is to stretch it. A purchase a year still leaves half the reported window unused, and that half is the margin.
The six-month myth
Until November 2026, this Journal said Citi and Bank of America close unused cards at six to 12 months. So did many other sites, none with a source. ActiveCred corrected the figure when the reports were checked. Citi is reported at 25 months or more, and Bank of America at about 24. The editorial policy explains how figures are now sourced.
The correction matters because the myth pushes cardholders toward needless effort on Citi cards and too little on the banks that are quicker, such as Wells Fargo at about 10 to 12 months and American Express at about 12. The issuer-by-issuer record has them all.
A letter after the fact
Citi's letter is reported to arrive once the account has already closed. That is legal. Regulation B excludes actions taken because of inactivity from the rules that require lenders to explain adverse decisions, and nothing requires notice beforehand.
It is also why the letter deserves a same-day response. The two things a Citi cardholder can still recover, the account and its points, both run on clocks that start at the closure date.
Reopening within 60 days
Citi is the one large bank with a reported reopening window. It runs 60 days from the closure, works by phone, and sometimes brings a hard inquiry. The points run on the same 60 days.
| When | What the record shows |
|---|---|
| Closure | The account closes; both 60-day clocks start |
| Afterwards | The letter arrives, after the fact |
| Within 60 days | Reopening by phone is reported, sometimes with a hard inquiry; ThankYou points can still be redeemed |
| After 60 days | A new application is the reported route; the redemption window has closed |
Call the number on the letter or on the back of the card, say the account was closed for inactivity, and ask three things.
- Can it be reopened as the same account? That keeps its opening date, history and limit.
- Will there be a credit check? A hard inquiry is a small cost, better known in advance.
- What happens to the ThankYou points? A reopened account may bring them back with it.
The reopening guide covers what other banks are reported to allow.
ThankYou points
Citi's ThankYou terms give 60 days after an account closes to redeem the points that belong to it, the most generous window among the large bank programs. The clock starts at the closure, so a letter that arrives a week later has already used a week of it.
Points can also be moved or redeemed before anything goes wrong. The rewards guide compares Citi with Chase, Amex and the others.
Checking a Citi card that has sat unused
The quickest test is a small purchase. If a $1 charge goes through and posts, the card is open and its clock has just been reset. If it is declined, the account may have been closed, or the bank's fraud checks may want to confirm the purchase; a large or unusual charge after months of silence can be refused while the account stays open. Citi's app or website shows a closed account as closed, or drops it from the list.
The credit report settles whether the account is open. Reports from all three bureaus are free every week at annualcreditreport.com, and an account the bank has closed carries a remark such as "closed by credit grantor". The date of the last purchase is on the statements. Five ways to check a card sets out the rest.
Only a purchase that posts to the statement counts as use. Payments, refunds and logging in do not reset the clock, and a balance transfer is not a purchase. What counts as activity has the detail.
The safe cadence
ActiveCred's rule is a cadence no longer than half the shortest reported closure, and never less often than once a year. Half of Citi's 25 months is more than a year, so a newly linked Citi card is charged once a year unless the cardholder picks another schedule.
A cardholder with cards from several banks may prefer every three months for all of them. It is the schedule ActiveCred gives a card from a bank with no reports, and it clears the shortest closure reported at any large bank, about 10 months at Wells Fargo, with seven months to spare.
Fee cards such as the Strata Premier ($95) post a fee each year, which appears to count as activity. The no-fee Double Cash, Custom Cash, Simplicity and Diamond Preferred cards are the ones that need a purchase. For a card whose last purchase date is known, the inactivity checker, set to Citi shows how far into the reported window it is and the date to use it by.
In short
Citi is not the six-month closer of folklore. It is reported at 25 months or more, and it tells the cardholder only once the card has gone. At a bank whose only warning is a notice of closure, the purchase has to come first.