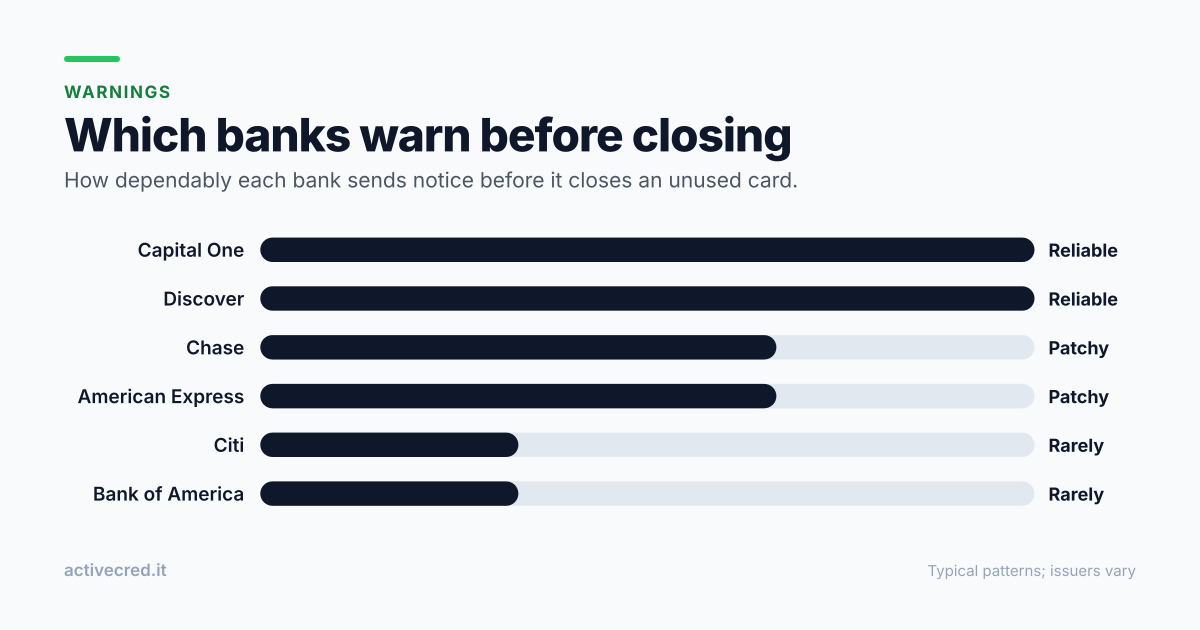
Issuers don't have to warn you before closing a card for inactivity. No federal requirement for advance notice, and each bank decides whether sending one is worth the cost. Some treat it as basic customer service; others skip it entirely. Whether you get a heads-up depends almost entirely on which bank issued the card.
Capital One and Discover are reliable. Chase and Amex (no-fee cards) are spotty. Citi and Bank of America rarely warn at all. Even reliable warners can miss you (wrong address, spam folder). The defense is regular activity on every card, not relying on the bank's courtesy.
See the automation or jump to pricingCapital One: the most reliable
Capital One sends a written notice 30 to 60 days before inactivity closure on virtually every consumer card. The notice arrives by physical mail at the address on file, and on recent app versions also appears as a banner reading "Action needed to keep your account active."
The text is direct: "You haven't used your [Card Name] account in over a year. To keep your account open, please make a purchase by [date]." A few specific suggestions usually follow ("a small purchase, a recurring subscription").
Caveat: the address-on-file matters. Move without updating Capital One and the notice goes to your old address. Update contact info in the app under Profile to Personal Information.
Discover: reliable, usually by email
Discover sends inactivity notices roughly 30 days before closure, primarily by email. Subject lines like "Important update about your Discover account" or "Use your card to keep it active."
The catch: email filtering. Discover's marketing email frequency is high, so notices often land in promotions folders. If you have an unused Discover card, check spam and promotions for any Discover messages in the last 60 days.
Discover is also unusual in that the in-app account record states the closure reason after the fact, useful when deciding whether to request reactivation.
American Express: depends on the product
Amex's notice behavior splits sharply by card type:
- Premium charge cards (Platinum, Gold, Green): rarely close because the annual fee itself counts as activity. When they do, Amex sends 30-day notice by email and mail.
- No-fee products (EveryDay, Cash Magnet, Blue Cash Everyday): can close at 12 to 18 months; notice rate is lower. Some closures happen with no warning.
- Business cards (Business Platinum, Business Gold, Plum): notices more reliable than no-fee consumer products.
For no-fee Amex products, treat as no-warning territory.
Chase: inconsistent, often silent
Chase's warnings are unpredictable. Personal cards (Sapphire lineup, Freedom Unlimited, Slate) often close without notice; the first signal is a closure letter or the closed status in the app. Premium cards with annual fees rarely close because the fee counts.
When Chase does send notices, they come by physical mail about 30 days before closure. The action ("make a purchase before [date]") is the same as other issuers.
The credit-card forum consensus matches: if you have a no-fee Chase card you've forgotten about, relying on Chase to notify you is gambling.
Citi: the least reliable
Citi has the lowest notice rate of the major issuers. On consumer cards (Double Cash, Custom Cash, Premier), closures often happen with no notice at all. You find out via your credit report or by trying to use the card.
Citi cobranded cards (American Airlines AAdvantage, Costco Anywhere Visa) sometimes follow the cobrand partner's retention practices, which can be more notice-friendly. For everything else: assume no warning, ever.
Bank of America: inconsistent, one nuance
BoA sends notices irregularly. Premium cards (Premium Rewards, Travel Rewards Elite) get them more often; no-fee cards usually don't.
BoA's distinguishing feature: the in-app "Inactive" label. A flag-but-not-yet-closed state visible on the account tile. If you see it, the card is on the closure track but still recoverable; a single purchase usually clears it. Catch: BoA doesn't proactively notify you the flag is applied. You only see it if you check.
Store cards (Synchrony, Comenity)
Most store credit cards (Macy's, Kohl's Charge, Amazon Store Card, Target REDcard credit version) are issued by Synchrony or Comenity. Both send notices inconsistently: Comenity slightly better, neither reliable.
Store cards close faster than bank-issued cards too, sometimes at 6 to 9 months, so the warning window is narrower even when notices do go out. Treat as highest-risk category.
The pattern: notices are a courtesy
Even reliable warners can't be counted on. Capital One mails notices but wrong addresses kill them. Discover emails them but filters bury them. Chase sometimes sends, sometimes doesn't. Citi mostly doesn't.
The defensive strategy that works isn't "I'll get a warning"; it's "no card ever gets close to the threshold." A regular activity cadence on every card, independent of issuer notice practices. Three implementations: a recurring subscription on each card, quarterly manual rotation, or automation that handles the whole portfolio.
Five signs a card is about to be closed
A written notice is only one of the signals, and the least dependable. Four others show up in places a cardholder can check without waiting for the bank.
- A notice by email or post. Subject lines run along the lines of "Action required to keep your account open" or "We haven't seen activity on your card recently". The notice gives 30 to 60 days. It often goes to an old email address or a previous home.
- A status label in the app. Bank of America shows "Inactive" and "Closed" as separate states. Capital One sometimes puts a banner at the top of the dashboard reading "Action needed to keep your account active". Any unfamiliar label on an unused card deserves a look the same day.
- An unannounced cut to the credit limit. Some banks reduce the limit on an idle card before they close it. Closure usually follows within 60 to 90 days.
- Statements stop arriving. An open card produces a statement every cycle, even at a $0 balance. Two or three months without one means the account has probably gone.
- The card still works in a phone wallet. This one misleads. Wallet payments can keep going through for 24 to 72 hours after a closure, so a tap that works proves nothing. Only a charge that posts to the statement does.
No bank telephones, and almost none sends a text or push alert about inactivity. Those channels are kept for fraud and payments.
When any of the five appears, the response is the same. Make a small purchase that day; it posts within 24 to 48 hours and resets the clock. Log in a week later to confirm the label has cleared, and call the bank if it has not. Then put a recurring charge on the card, so that the next warning is not needed.
In short
Capital One and Discover send notices most consistently. Chase and Amex are unreliable on no-fee products. Citi and Bank of America rarely send any. Store cards are highest-risk with the narrowest warning windows.
The right operating assumption is that you may never get a warning. Build the defense around regular activity, not the bank's courtesy.