Every major credit-card issuer runs an automated scan, usually monthly, that checks every consumer account for inactivity and flags the ones at risk of closure. For unused cards sitting at a $0 balance with no recent charges, this is the machinery deciding their fate. Knowing what the scan checks shows exactly what it takes to pass it.
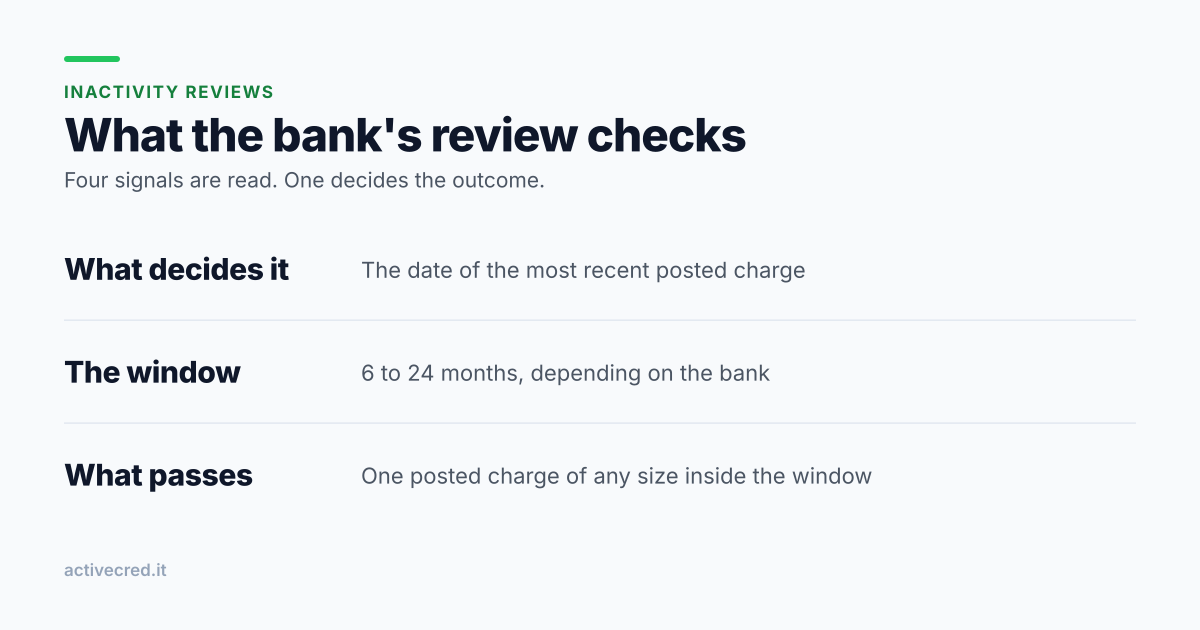
The review checks four signals, but only one is decisive: the date of the most recent posted charge. If the gap exceeds the issuer's threshold (6 to 24 months, depending), the account is flagged. One $1 posted charge inside the window passes.
See the automation or jump to pricingThe four signals an inactivity review checks
Every issuer's review uses some combination of the same four signals. Weighting differs; shape is consistent across the industry.
1. Date of last posted transaction
The dominant signal, by far. The query picks the most recent posted transaction and computes how many days have passed. If that number exceeds the issuer's threshold (typically 12 months for consumer cards), the account fails.
Two details matter. The transaction must have posted, not just been authorized; pending, declined, or reversed transactions don't count. And it must be a charge, not a payment. Issuers track outbound merchant transactions, not the inbound payments that clear the balance. A $1,000 payment on a $0 balance doesn't move the needle.
2. Statement balance trend
Secondary. The review looks at the last 6 to 12 statement balances and asks: was there activity? If every statement shows $0.00 across the window, that supports the flag. One non-zero balance somewhere in the window is evidence of a real account even if the most recent statement is $0.
3. Credit-limit utilization across the portfolio
Some issuers (notably Chase and Citi) factor in the overall relationship. Given three cards with the same issuer, two used heavily and one dormant, they're more likely to close the dormant one because the other two already give them plenty of business. A single dormant card with no other products is more likely to stay open, in case its owner becomes an active customer later.
4. Customer-relationship value
How long the customer has been with the bank, premium products held, FICO trend (where available), partner products like checking. A 15-year customer with a clean history gets longer leeway than a 1-year customer. The review isn't blind to context; it just doesn't publish its weighting.
What the review does NOT check
Three common assumptions that don't matter:
- Logging in. Engagement metrics aren't part of the query. The review looks at posted transactions.
- Calling customer service. The rep can note the call, but the automated review doesn't read notes.
- Making a payment. Payments are credits, not charges. Paying off a $0 balance is one of the most common misconceptions about keeping a card alive.
How to pass
One posted charge inside the issuer's window. The size doesn't matter: $1 and $1,000 produce the same boolean (date < threshold = pass). Three durable approaches:
A recurring subscription
Pick a recurring subscription that is already being paid for and put it on the dormant card, with autopay. The review finds a charge in the last 30 days every time. Best for 1 to 2 unused cards. It becomes unwieldy at 4 or more: it gets hard to remember which subscription is on which card, and any cancellation opens an inactivity gap nobody notices.
The quarterly manual charge
One small purchase per unused card every 90 days. Coffee, a song, a digital download, paid off the same day. Free, but it depends on remembering and following through. Best for 1 to 3 cards and a disciplined owner. Fails unnoticed when life gets busy.
The automation approach
A service that runs a tiny authorized charge on each card on a schedule. The mini-charge strategy: one posting per card per month, no spending required. Best for 3+ unused cards or anyone who'd rather not think about it.
What happens on a fail
The flag-to-closure pipeline:
- Flagged. Account marked for review-board attention. Bank of America explicitly labels this status "Inactive" in the customer app: open but on watch.
- Decision. Within ~30 days, a human (or another automated step) reviews flagged accounts. Outcome: close, downgrade to a no-fee product, or leave open with a credit-limit reduction.
- Notice (optional). Capital One and Discover routinely send 30-day notices. Chase, Amex, Citi, and BoA often don't. The notice says "make a purchase by [date]" to prevent closure.
- Closure. If nothing is done, the closure goes through. The credit report shows "Closed by credit grantor" within 30 days.
For a card that has been flagged but not yet closed, one posted charge usually clears the flag at the next review cycle. Speed matters: once the closure has been processed, reactivation is much harder than prevention was.
In short
An inactivity review is a database query, not a moral judgment. "Has this account had a posted transaction in the last X months?" The answer determines what happens. Nobody needs to know the exact threshold to pass: with at least one transaction posting per quarter on each card worth keeping, the review returns "active" every cycle.
The simplest way to do that across multiple cards is to delegate the cadence to something that doesn't forget.